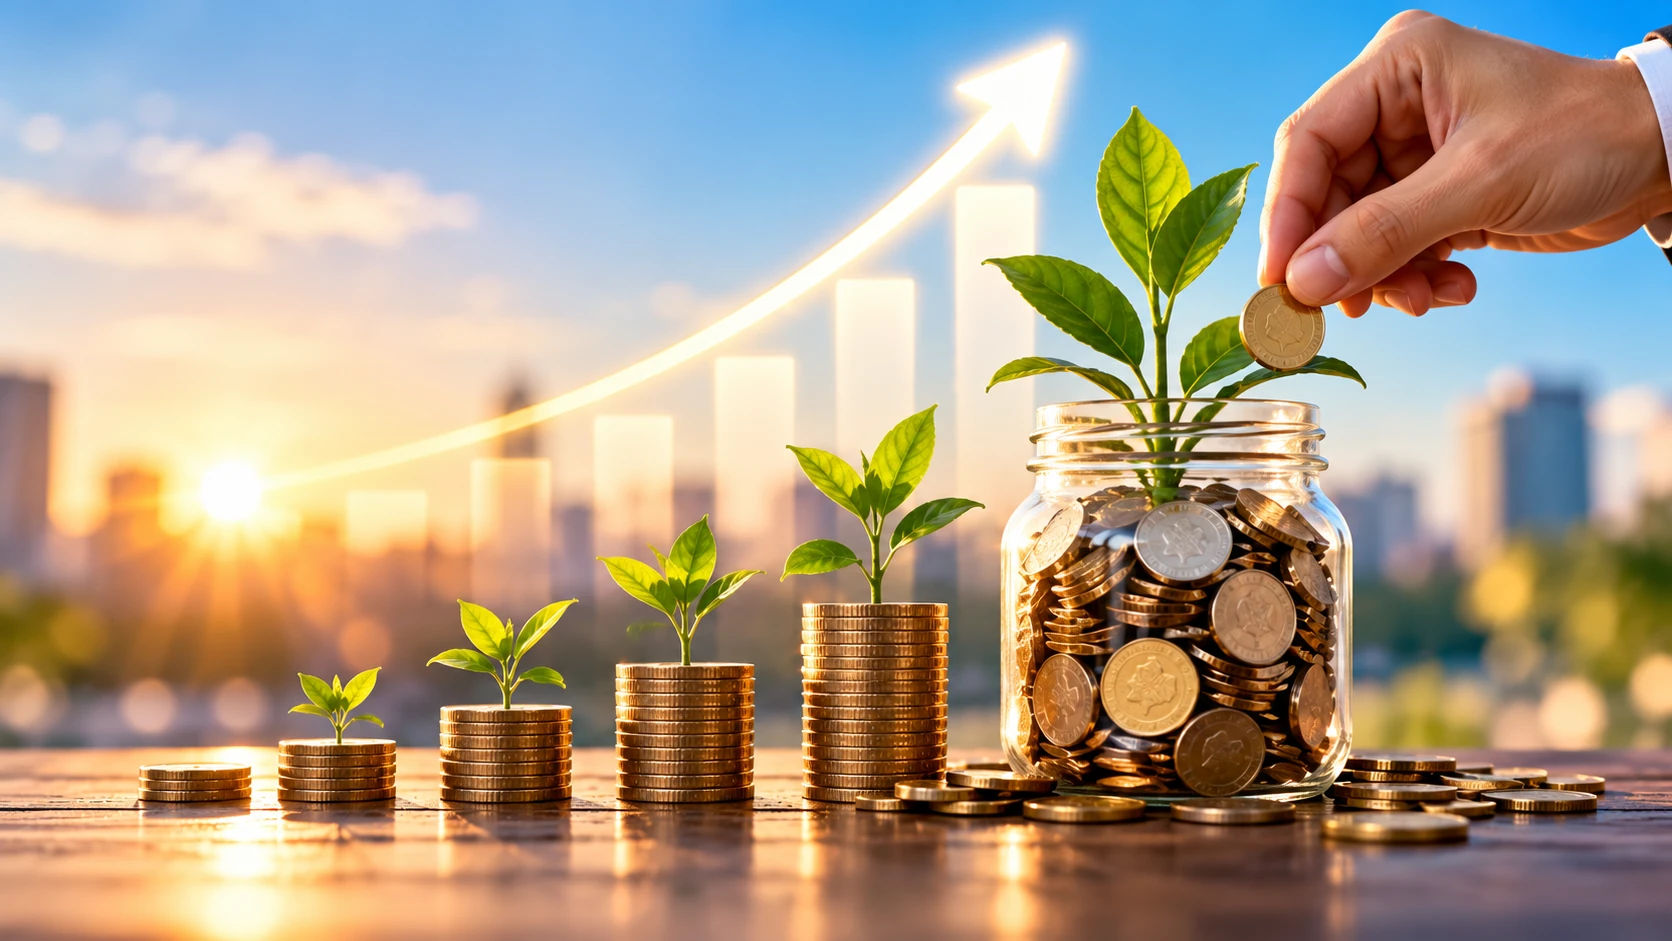
Saving money is an important part of financial planning, but simply putting money aside is only one part of the process. When savings earn returns and those returns are added back to the balance, future returns can be calculated on the larger amount. This effect is known as compound growth.
Over long periods, compounding can make a significant difference, particularly when contributions are made consistently.
What Is Compound Interest?
Compound interest means that returns earned on money can themselves begin earning returns.
For example, suppose you deposit money into an account that earns interest. The initial deposit earns interest during the first period. If that interest remains in the account, the following period’s interest may be calculated on both the original deposit and the accumulated interest.
Time Is One of the Most Important Factors
Compounding becomes more powerful when money remains invested or saved for longer periods.
Someone who begins saving earlier may have more time for returns to accumulate and generate additional returns. This is one reason long-term financial planning can be valuable even when the initial amounts are relatively small.
Starting early does not mean you need to begin with a large amount. Consistency and time can both play important roles.
Regular Contributions Can Strengthen Growth
Compound growth is not limited to a single initial deposit. Regular contributions can add to the amount that is available to earn returns.
For example, someone who contributes a fixed amount every month is continually adding new money to the savings or investment balance. Over many years, those contributions and their accumulated returns can potentially grow together.
The actual outcome depends on the interest or investment return, contribution amount, frequency, fees, taxes, and other factors.
Higher Returns Can Change the Outcome
The rate of return has an important effect on long-term growth. A higher rate can produce greater growth if all other factors remain equal.
However, higher potential returns generally come with different levels of risk depending on the financial product. A savings account, fixed deposit, bond, mutual fund, or equity investment does not have the same risk and return characteristics.
Therefore, chasing the highest possible return is not always appropriate for every financial goal.
Compounding and Saving Discipline
The mathematical effect of compounding works best when money remains invested or saved instead of being regularly withdrawn.
Frequent withdrawals can reduce the amount available to generate future returns. Creating separate accounts for different goals can sometimes make it easier to leave long-term savings untouched.
Understand the Difference Between Saving and Investing
Compounding can occur in different financial products, but the mechanism and risks vary.
Bank deposits may provide stated interest according to their terms. Investments such as mutual funds and stocks can produce returns through changes in value and income, but their returns are not guaranteed and can fluctuate.
Before choosing a financial product, consider your time horizon, financial goals, liquidity needs, risk tolerance, taxes, and applicable fees.
Inflation Matters
Seeing your savings balance increase does not automatically mean your purchasing power is increasing at the same rate.
Inflation causes prices to rise over time, which means money may buy fewer goods and services in the future. When evaluating long-term savings, it can be useful to consider whether the expected return is keeping pace with inflation after accounting for taxes and costs.
Avoid Unnecessary Withdrawals
Long-term growth can be interrupted when money is repeatedly taken out for short-term purchases.
Creating separate funds for emergency expenses, short-term goals, and long-term goals can help prevent you from using long-term savings for routine expenses.
An emergency fund can be particularly useful because it provides accessible money for unexpected costs without necessarily requiring you to disturb long-term investments.
Small Amounts Can Still Matter
People sometimes believe that investing or saving is worthwhile only when they have a large amount of money. In reality, regular small contributions can become meaningful over long periods.
The important factors include consistency, time, the return earned, and the costs associated with the financial product.
As income increases, you can consider gradually increasing your contribution rather than waiting until you can afford a much larger amount.
Review Your Progress
Financial goals can change over time. Review your savings strategy periodically to determine whether your contributions, time horizon, and chosen financial products still match your objectives.
Avoid making decisions based solely on short-term market movements if you are working toward a long-term goal. For investment decisions, professional financial advice may be appropriate when the circumstances are complex.
Final Thoughts
Compound interest demonstrates why time can be a powerful factor in financial growth. Money that earns returns can generate additional returns, and consistent contributions can further increase the amount available to compound.
The exact results will depend on the return rate, contribution schedule, taxes, fees, and financial product involved. Nevertheless, starting early, contributing consistently, understanding risk, and allowing savings to remain invested or deposited for the intended period can help make the most of long-term compounding.